How to Save for a Goal: a Simple Plan That Sticks
A trip, a renovation or an emergency fund: how to turn "I should save" into an amount, a date and a regular contribution — and keep going past month one.
· 5 min read
"I should start saving" is one of the most common money goals — and one that usually stays an intention. The reason is almost always the same: the goal has no amount, no date and no separate place where the money lives. This guide gives you five steps that turn "I want to save" into a plan: how much to set aside, where to keep it and how not to spend it by accident.
Step 1: name the goal and work out the amount
"Save for a holiday" is a wish, not a goal. A goal is "$3,000 for two weeks in Portugal by June 1". The more specific it is, the easier it is to stick to:
- Name. Short and clear to you: "Holiday", "Kitchen renovation", "6-month emergency fund".
- Amount. List the big items and add a 10–15% buffer — prices rarely turn out lower than you expected.
- Date. A specific one. Without it you can't work out a contribution, and the goal slides to "later".
If you have several goals, don't split your savings evenly across all of them. Pick one or two that matter most; the rest can wait.
Step 2: work out the contribution
Contribution = (amount − already saved) ÷ number of weeks or months until the date.
Example: you need $3,000 in 6 months and already have $600. That leaves $2,400 — $400 a month, or about $92 a week. If that doesn't fit your budget, you have three levers: move the date, lower the amount, or find something to cut. An honest calculation now beats a disappointment a month before the trip.
It works best when contributions match your income rhythm: paid monthly — save monthly, on payday. As long as the money sits on your everyday card, it tends to get spent.
Step 3: a separate account for the goal
The biggest mistake is saving on the same card you buy groceries with. The balance grows and shrinks without you noticing, and six months later you can't tell how much of it is the holiday and how much is just leftover.
A separate savings account fixes that: whatever sits there belongs to the goal. If your bank lets you open several savings "pots" or "spaces", use one per goal.
If the goal is in another currency — say, a trip you'll pay for in euros — save in that currency from the start. That way the exchange rate on the day you leave won't eat part of what you saved.
Step 4: pay yourself first
"I'll save whatever is left at the end of the month" almost never works: there's nothing left. The opposite order does — the transfer to the goal comes first, everything else after. What helps:
- an automatic transfer in your bank on payday;
- a reminder on contribution day if there's no automatic transfer;
- a fixed amount, not "whatever I can".
Step 5: check against the plan once a month
Once a month, compare what you've saved with where the plan says you should be. If you're behind, decide right away: top up, raise the contribution or move the date. A small gap is easy to close; a big one a month before the deadline isn't.
When you reach the goal, close it on purpose: spend it on what you saved for, and move what's left to the next goal or your emergency fund.
Example: an emergency fund in a year
A household spends about $2,500 a month and wants three months in reserve: $7,500 by next December. There's $1,000 saved already, which leaves $6,500 over 12 months — about $540 a month.
The fund gets its own savings account, and the bank moves $540 there automatically on payday. In April an unexpected car repair means the contribution is skipped. The monthly check shows the plan expects $2,620 and the account holds $2,080. The fix: add an extra $135 for the next four months. By December the fund is complete, with no "wait, where did the money go?".
How to do it in Buddzy
Buddzy has a Goals section for exactly this, on the Basic and Premium plans:
- you set a name, an amount, a currency and a date — Buddzy opens a dedicated savings account for the goal;
- the app works out the contribution you need to make it in time and, if you like, sets up a contribution schedule with transfer reminders every week or every month;
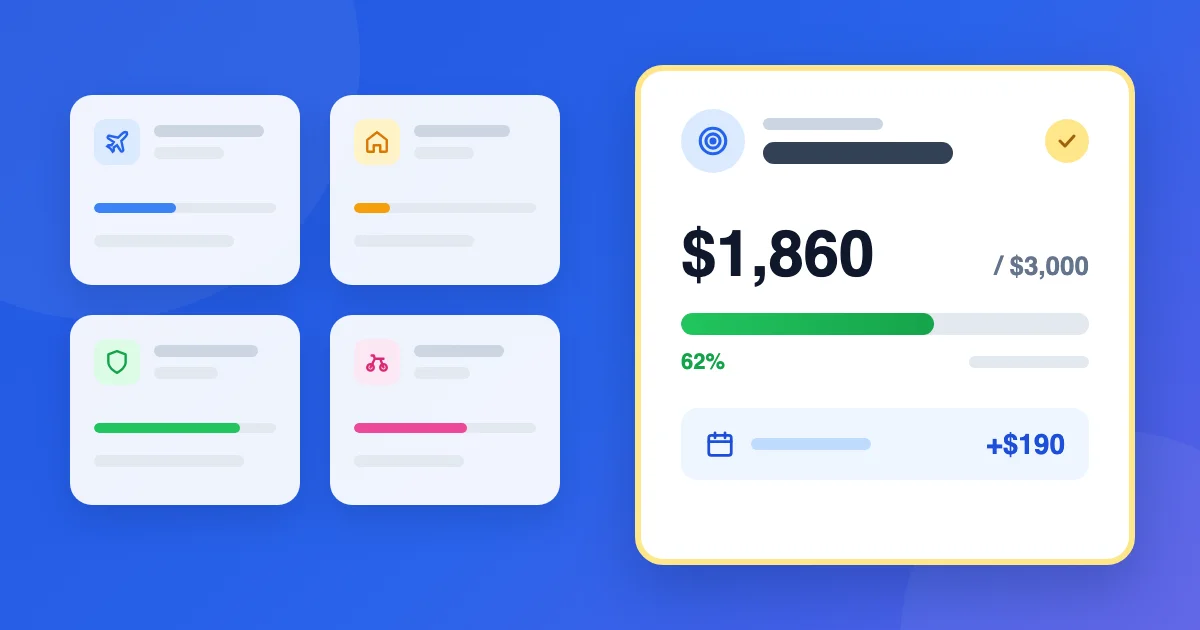
- each goal card shows how much you've saved, how much is left and where the plan says you should be now, and its status tells you whether you're on track or behind;
- goals show up on the dashboard, and each has its own page with a savings chart and a forecast;
- when a goal is reached, you close it and move what's left to any other account in one step.
A goal's money is an ordinary Buddzy account, so it counts toward your total balance without mixing with everyday spending. The Free plan includes up to 5 accounts and 200 transactions a month; goals and category budgets come with Basic — see pricing.
Checklist
- The goal has a name, an amount with a buffer and a date.
- The contribution is worked out and fits your budget.
- A separate account for the goal, in the currency you'll spend it in.
- The transfer happens on payday, automatically or by reminder.
- Once a month: check against the plan and act if you're behind.
If you're just getting started with budgeting, begin with how to budget as a couple; if you save in one currency and spend in another, see how to track expenses in multiple currencies.
Read next
 GuideExpense tracking
How to Track Expenses Faster: 5 Habits and Auto-Fill Rules
People quit expense tracking because of the routine. Five habits that cut each entry to seconds, plus rules that fill in categories for you.
· 5 min read
 GuideExpense tracking
How to Keep Receipts and Warranties So You Can Find Them
Which receipts are worth keeping, for how long and where: a simple system for warranties, big purchases and documents — no shoebox of faded paper.
· 5 min read
 GuideExpense tracking
How to Export Your Zenmoney Data: CSV and Moving Apps
Where to find Zenmoney's CSV export, how to open the file in Excel without garbled text, and how to move your records to another app without any files.
· 6 min read